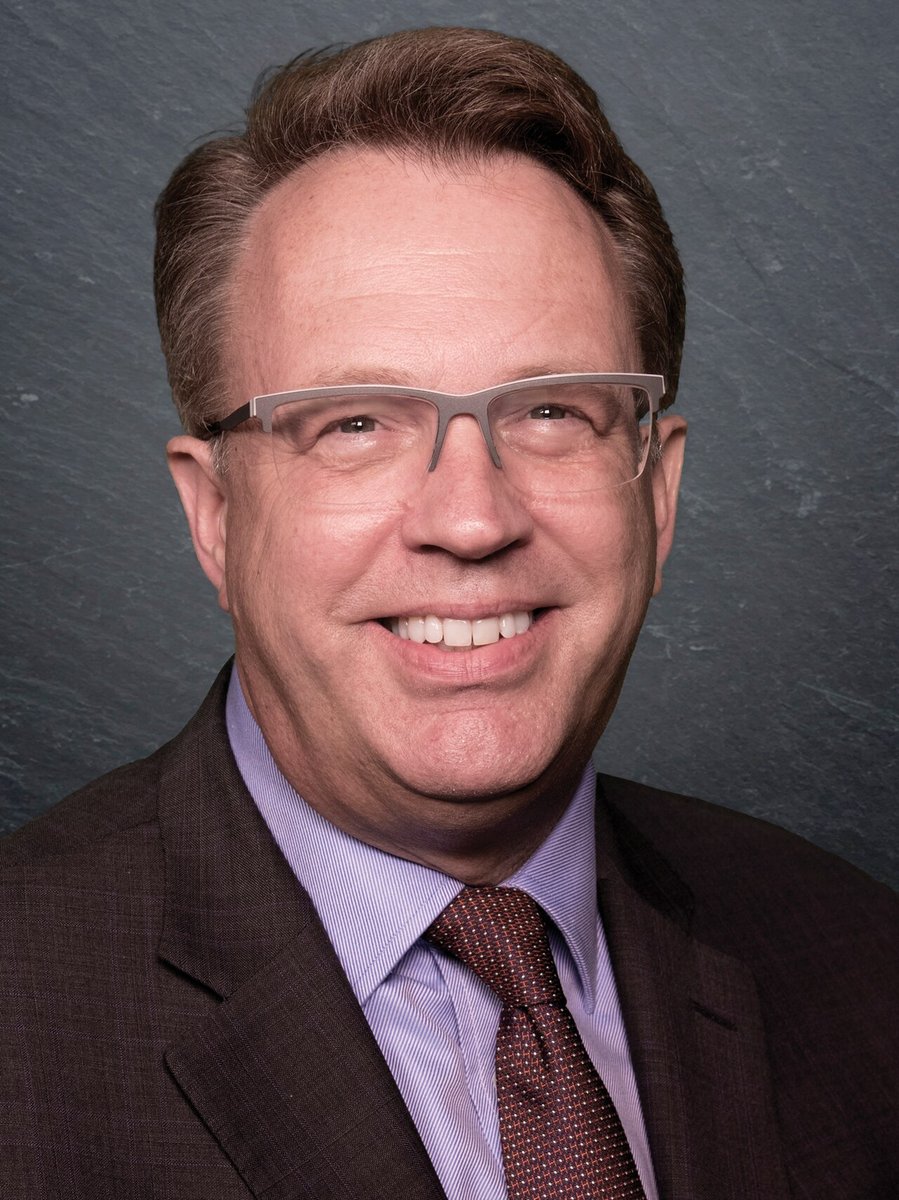
John Williams, president of the Federal Reserve Bank of New York, told an audience at the University at Buffalo on September 29, 2026 that the central bank can afford to wait before raising interest rates again — while leaving one more increase on the table before the year is out.
"If the economy evolves in a manner broadly consistent with my forecast, one further upward adjustment of the federal funds target range may be appropriate late this year," he said. But he was equally clear about the pace: "With the policy action we took at our September meeting, there is no need for urgency, and we have time to gather more information."
The Federal Open Market Committee raised the target range by a quarter of a percentage point at that September meeting, to 3.75% to 4%.
Inflation at 3.7%, and three reasons for it
Williams did not soften his description of the problem. "At 3.7 percent, inflation is unquestionably too high," he said, while forecasting that overall inflation would come in at 3.5% for this year, slow to just above 2% next year, and reach the Fed's 2% target by 2028.
He attributed the persistence to three forces. Tariffs on imports pushed prices up but are no longer adding to inflation. Supply-chain disruption and energy prices tied to conflicts in the Middle East are still feeding through. And demand remains robust, in part because of investment linked to artificial intelligence — a category that now shows up in a central banker's inflation accounting.
On growth and jobs, his forecast is unremarkable by design: real GDP expanding roughly 2% to 2.25% this year and next, a labour market he described as solid and even marginally stronger at the margin, and an unemployment rate edging down to about 4% over the coming year. Workforce growth, he noted, is no longer contributing much to expansion.
The hawks in the same day's mail
Three other Fed officials spoke on September 29, and two of them leaned harder than Williams. Governor Michael Barr said further policy adjustments are likely needed and that he does not see a clear trend back to 2% inflation on a timely basis. Austan Goolsbee, of the Chicago Fed, described inflation running above target for five and a half years as "playing with fire." Alberto Musalem, of the St. Louis Fed, addressed how the Committee communicates rather than where rates go next.
Markets read the spread and priced roughly a two-in-three chance of an increase at the October meeting, with higher odds for December.
What the long end is saying
The bond market is not waiting for the Committee to make up its mind. According to the Treasury Department's daily yield curve, the 10-year note closed at 5.26% on September 29 and the 30-year bond at 5.59% — up from 5.17% and 5.49% on September 25, and both at multi-year highs.
That combination is worth sitting with. The policy debate in Washington is over a single quarter-point move; the yields investors demand to lend to the United States for thirty years have climbed roughly ten basis points in four sessions. A long end rising while the short-rate question is this narrow is not a market pricing a tighter Fed. It is a market pricing inflation, and borrowing, that last.
Reporting from the Federal Reserve Bank of New York, the U.S. Department of the Treasury and InvestingLive.